Bhabishyat Credit Card 2026: ₹5 Lakh Collateral-Free Loan for Youth – Eligibility, 4% Interest, Status & What’s New
Last checked: 3 November 2026. The West Bengal Bhabishyat Credit Card scheme was launched to help young people start their own businesses without giving any security to the bank. It offers collateral-free loans of up to ₹5 lakh, with government support on interest. In 2026, after the change of government, many young people want to know whether the Bhabishyat Credit Card is still running and whether a new scheme is coming.
This guide explains what the Bhabishyat Credit Card offers, who can apply, the interest rate, documents, how to apply, what happened in 2026 and how it compares with the older Karma Sathi scheme and the proposed Banglar Udyam Credit Card.
Quick answer: The Bhabishyat Credit Card scheme opened on 1 April 2023 and offers collateral-free loans of up to ₹5 lakh, with seed money of up to ₹25,000. From April 2024, borrowers were reported to pay 4 percent interest, with the state paying the rest. As of 3 November 2026, the new government has not announced a clear decision on the scheme, while a new Banglar Udyam Credit Card has been proposed.
What is the Bhabishyat Credit Card?
The Bhabishyat Credit Card (West Bengal Bhabishyat Credit Card Scheme, WBBCCS) is a state scheme for young entrepreneurs. “Bhabishyat” means future. Under the scheme, an approved young person gets a credit facility from a bank to start or run a small business, with the state government standing behind the loan.
It replaced the earlier Karma Sathi Prakalpa, which offered loans of only up to ₹2 lakh. The idea was to make bigger, cheaper and simpler loans available to young people who have a business idea but no property to offer as security. The scheme is linked to the state’s MSME department.
Bhabishyat Credit Card at a glance
| Point | Details (as reported) |
|---|---|
| Started | Applications opened on 1 April 2023 |
| Department | MSME, Government of West Bengal |
| Maximum loan | ₹5 lakh |
| Collateral | Not needed; the government acts as guarantor |
| Seed money | Up to ₹25,000 |
| Borrower interest | 4 percent from April 2024, with the state paying the rest |
| Age | 18 to 45 at launch; a 2025 report mentioned 18 to 55 |
| Residence | Permanent resident of West Bengal |
| Portal | bccs.wb.gov.in |
How much loan and interest?
The Bhabishyat Credit Card offers a business loan of up to ₹5 lakh. The exact amount depends on your project and the bank’s assessment, so you may be sanctioned less than you ask for.
On interest, a 2025 report said banks charged 10 to 12 percent, but from April 2024 the borrower paid only 4 percent, and the state paid the difference. This makes the loan much cheaper than a normal business loan, provided you repay on time.
Approved applicants could also get seed money of up to ₹25,000 to help with the first costs of the business.
Who can apply for the Bhabishyat Credit Card?
Based on scheme information and reports, an applicant should:
- Be a permanent resident of West Bengal (some sources say living in the state for the past ten years).
- Fall within the age limit (18 to 45 at launch; a later report mentioned up to 55).
- Want to start or run a small business in manufacturing, services, trading or agro-based activity.
- Have a clear business proposal.
- Belong to a family where no other member has the same benefit, as some sources say only one person per family is eligible.
Business activities covered
- Small manufacturing units, such as food processing, tailoring or handicrafts.
- Services, such as repair shops, beauty services, tuition centres or transport.
- Trading, such as retail shops and small wholesale.
- Agro-based units, such as poultry, dairy-linked work or nurseries.
Who should think twice before applying
A loan is a responsibility. The Bhabishyat Credit Card may not be right for you if:
- You do not yet have a clear business idea.
- You have no experience or training in the business you plan.
- Your expected income cannot cover the monthly repayment.
- You already have unpaid loans that are overdue.
In such cases, it is better to train, plan and save a little first, then apply.
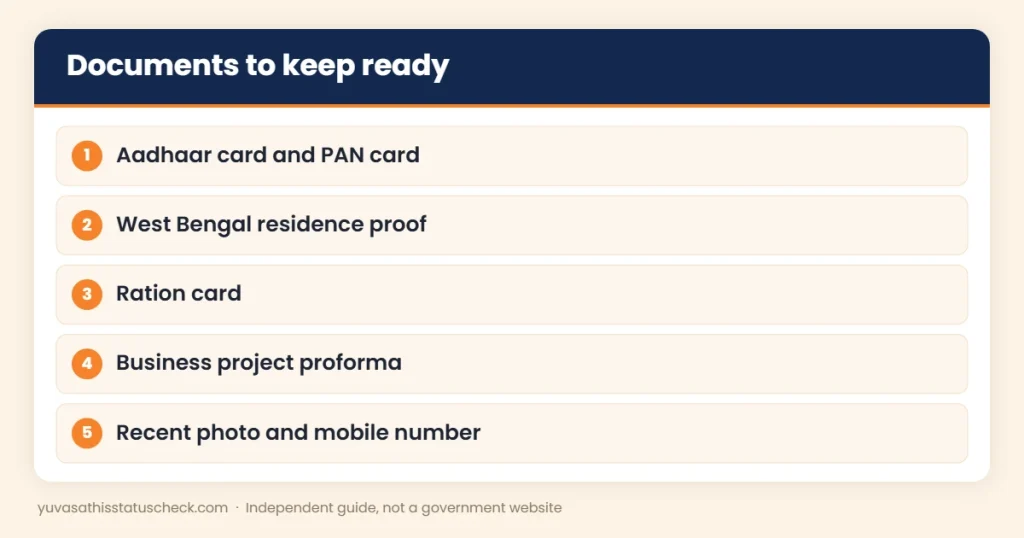
Documents needed for the Bhabishyat Credit Card
- Aadhaar card.
- PAN card.
- Proof of permanent residence in West Bengal; our residential certificate West Bengal guide explains how to get one.
- Ration card copy.
- Business project proforma or report.
- Recent passport-size photo.
- Active mobile number and bank details.
- Caste certificate, if applicable; see our caste certificate West Bengal guide.
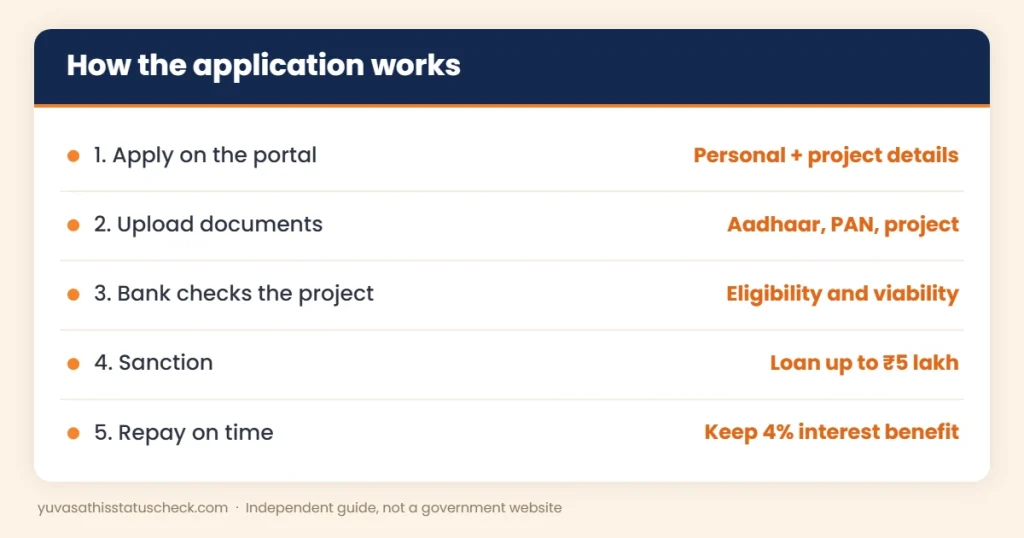
How to apply for the Bhabishyat Credit Card
- Open the official portal, bccs.wb.gov.in, and choose the online application option.
- Fill in your personal details, address and contact information carefully.
- Enter your business idea, the amount needed and project details.
- Upload the required documents.
- Submit and note your application number.
- The application goes to a bank, which checks eligibility and the project.
- If approved, the bank sanctions the loan and you complete the bank’s formalities.
Fill in every field carefully, because a small mistake in your name or address can hold up the bank check. Registration on the portal was free. Never pay an agent to submit or approve a Bhabishyat Credit Card application.
How to prepare a strong project proforma
The project proforma is the heart of your application. Banks use it to decide whether your business can repay the loan. Include:
- What you will do: the product or service and who will buy it.
- Where: the location, and whether it is owned or rented.
- Start-up cost: machines, furniture, stock, licences and the first months’ rent.
- Your contribution: any savings you will put in.
- Monthly income and expenses: realistic sales, costs and profit.
- Repayment plan: how much you will pay the bank each month.
A clear one or two page proforma with honest numbers is better than a long one with guesses. Ask a bank officer or the district MSME office for a sample.
How to check Bhabishyat Credit Card status
- Log in to the official portal with your registered details.
- Open your dashboard and the application details.
- See whether your application is pending, forwarded to a bank, sanctioned or rejected.
- If it is with a bank, visit the branch with your application number.
What the status may mean
| Status | Meaning | What to do |
|---|---|---|
| Submitted | Your form has been received | Wait for checking |
| Forwarded to bank | A bank is reviewing it | Visit the branch with documents |
| Sanctioned | The bank has approved the loan | Complete bank formalities |
| Disbursed | Money has been released | Start the business and repay on time |
| Rejected | The proposal or papers did not pass | Ask the reason; improve and reapply if allowed |
Simple business ideas for a loan of up to ₹5 lakh
- A grocery, stationery or medicine-related retail shop (with the right licences).
- A mobile and electronics repair centre.
- A tailoring or boutique unit.
- A small food business, such as a tiffin service or snack stall.
- A cyber cafe and printing centre near schools or offices.
- A small poultry or mushroom farming unit.
- A beauty parlour or salon.
Pick an idea that fits your skills and the demand in your area. Talk to people who already run similar businesses before you decide.
How well did the scheme do?
A Millennium Post report in April 2025 said more than 40,000 applications worth about ₹925 crore were sanctioned in 2024-25, banks disbursed about ₹590 crore for 28,000 applications, and the subsidy on sanctioned cases was about ₹65 crore. It also mentioned special drives with district magistrates and banks to clear pending cases. This shows the Bhabishyat Credit Card reached far more people than the older Karma Sathi scheme. It also shows that the gap between sanction and disbursal can be large, so applicants should keep following up with their bank even after sanction.
Bhabishyat Credit Card in 2026: what is the status?
After the new state government took office in May 2026, it has not published a clear decision on the Bhabishyat Credit Card. We have not seen an order closing it, nor a notice of a fresh application round under the new government.
At the same time, a new scheme called the Banglar Udyam Credit Card has been described as a promise of the ruling party. A July 2026 article said it could offer up to ₹10 lakh, split into a grant and an interest-free loan, but it also said guidelines, a portal and even the implementing department had not been confirmed. Treat these figures as unconfirmed until an official notice is published.
What should applicants do now?
- If you already have a loan: keep repaying on time. Your loan terms do not change because of a political change, and good repayment protects your credit record.
- If your application is pending: check its status on the portal and with your bank. Ask whether it is still being processed.
- If you want to apply now: check the official portal for whether new applications are open. If not, prepare your documents and project report so you are ready when a scheme opens.
What if the scheme changes?
Schemes are sometimes renamed, merged or replaced when governments change. If that happens:
- Existing loans usually continue on their agreed terms with the bank.
- Pending applications may be moved to a new scheme or asked to reapply.
- Interest support rules for existing borrowers would normally be explained in a government order.
Keep all your loan papers, sanction letters and repayment receipts safe, so you can prove your status under any new rules.
Build a good credit record
Repaying a business loan on time builds your credit history, which helps you get bigger loans later to grow your business. Check your loan account statement regularly, keep enough money in your account before each due date and never ignore messages from the bank.
Bhabishyat Credit Card vs Karma Sathi vs Banglar Udyam
| Point | Karma Sathi Prakalpa | Bhabishyat Credit Card | Banglar Udyam Credit Card |
|---|---|---|---|
| Started | September 2020 | 1 April 2023 | Proposed in 2026 |
| Maximum support | ₹2 lakh loan | ₹5 lakh loan | Up to ₹10 lakh (reported, unconfirmed) |
| Extra help | 15% subsidy up to ₹25,000 | Seed money up to ₹25,000; 4% interest | Grant plus interest-free loan (reported) |
| Status | Superseded | No clear 2026 decision seen | Guidelines not released |
For the older scheme, read our Karma Sathi Prakalpa guide.
How to plan your repayment
Even at 4 percent interest, you must repay the loan in monthly instalments. Here is a simple example to help you plan. These figures are only an illustration; the actual tenure and terms are set by your bank.
| Loan amount | Interest | If repaid over 5 years | Approximate monthly instalment |
|---|---|---|---|
| ₹2 lakh | 4% | 60 months | About ₹3,700 |
| ₹3 lakh | 4% | 60 months | About ₹5,500 |
| ₹5 lakh | 4% | 60 months | About ₹9,200 |
Your business should earn enough every month to pay this instalment and still cover your own living costs. Keeping the 4 percent benefit usually depends on paying on time, so a missed payment can cost you more.
3 real-life examples
Arpan, 29, Siliguri: He used a Bhabishyat Credit Card loan of ₹3 lakh to set up a small printing and photocopy shop near a college. He repays about ₹5,500 a month from his earnings.
Nasima, 26, Murshidabad: She started a tailoring unit with two machines and a small loan. Her seed money helped her buy the first stock of cloth.
Subrata, 34, Purba Medinipur: His application was stuck at the bank. He visited the branch with his application number and a clearer project report, and the bank processed it after a few weeks.
Mistakes to avoid
- Applying on fake websites that copy the scheme name.
- Asking for the maximum ₹5 lakh when a smaller amount would do.
- Using the loan for personal expenses.
- Missing repayments and losing the interest benefit.
- Giving wrong information about residence, age or family.
- Paying agents for “guaranteed” approval of a Bhabishyat Credit Card.
Tips for getting your loan approved
- Prepare a short, realistic project report with costs and expected income.
- Choose a business you understand or have trained for.
- Keep your Aadhaar, PAN and bank details matching exactly.
- Ask for an amount you can repay comfortably.
- Visit the bank branch to explain your plan in person.
- Follow up regularly with your application number.
Offices that can help
For questions about a Bhabishyat Credit Card application or loan, start with the bank branch handling your case. If that does not help, contact the district MSME office or ask at your Block Development Office or Sub-Divisional Office. Special drives with district officials and banks have been held in the past to clear pending cases, so ask whether any such camp is planned in your district.
Other options for young entrepreneurs
| Option | What it offers (in general) | Where to check |
|---|---|---|
| PMEGP (central) | Subsidy-linked loans for new micro enterprises | PMEGP portal |
| PM Mudra Yojana (central) | Small business loans through banks | Mudra website |
| State startup funds | ₹40 crore incubation and ₹60 crore venture funds announced in Budget 2026-27 | State notices |
See our West Bengal budget 2026 summary for the startup funds. If you are not ready to start a business, the new monthly allowance for unemployed youth may help while you look for work; read our Yuva Shakti scheme guide.
Quick checklist
- Aadhaar, PAN and residence proof ready.
- A short project report with real numbers.
- Bank account with matching name details.
- A plan for monthly repayment.
- Your Bhabishyat Credit Card application number saved, if you have applied.
Frequently asked questions
What is the Bhabishyat Credit Card?
It is a West Bengal scheme that gives young people collateral-free business loans of up to ₹5 lakh, with government support on interest.
When did the Bhabishyat Credit Card scheme start?
Applications opened on 1 April 2023.
What interest do borrowers pay?
A 2025 report said borrowers paid 4 percent from April 2024, with the state paying the rest of the bank’s interest.
Is collateral needed?
No. The loans are collateral-free, with the government acting as guarantor.
What is the age limit?
Reports gave 18 to 45 at launch, and a 2025 report mentioned 18 to 55. Check the portal for the current rule.
Is the Bhabishyat Credit Card still running in 2026?
The new government has not announced a clear decision as of 3 November 2026. Check the official portal and your bank for the current position.
What is the Banglar Udyam Credit Card?
A proposed new scheme described as a promise of the ruling party, reported to offer up to ₹10 lakh. Guidelines and a portal have not been released.
Do I still have to repay my loan?
Yes. Loans must be repaid as agreed, whatever happens to the scheme.
Sources we checked
- Millennium Post, 28 April 2025: start date, ₹5 lakh limit, seed money, 4% interest, sanctions and disbursal.
- BankBazaar: Bhabishyat Credit Card: eligibility, documents and steps.
- IMPRI: Karma Sathi Prakalpa: replacement of Karma Sathi by Bhabishyat Credit Card from 1 April 2023.
- GovtSchemesIndia: Banglar Udyam Credit Card: proposed new scheme, status as of July 2026.
Disclaimer: yuvasathisstatuscheck.com is an independent information website. It is not connected with the Government of West Bengal or any bank. This is general information, not financial advice; check official sources before applying for a loan.