Karma Sathi Prakalpa 2026: Is the ₹2 Lakh Youth Loan Scheme Still Open? Status, Old Loans & Best Alternatives
Last checked: 3 November 2026. Karma Sathi Prakalpa was a West Bengal scheme that offered soft loans of up to ₹2 lakh to unemployed young people who wanted to start their own business. Many people still search for it in 2026, hoping to apply. But the scheme you may be looking for has changed.
If you are planning to start a small business, it is important to know which scheme is actually open. This guide explains what Karma Sathi Prakalpa offered, how it worked, why it was replaced, what happens to old applicants and borrowers, and which loan options young people in West Bengal can use today.
Quick answer: Karma Sathi Prakalpa was launched in September 2020 with soft loans of up to ₹2 lakh and a 15 percent subsidy (up to ₹25,000). From 1 April 2023, it was superseded by the Bhabishyat Credit Card scheme, which offered loans of up to ₹5 lakh. As of 3 November 2026, we have not seen any new Karma Sathi application round.
What is Karma Sathi Prakalpa?
Karma Sathi Prakalpa was a self-employment scheme of the Government of West Bengal. It was launched in September 2020, when many young people had lost work during the Covid lockdowns. The goal was to help unemployed youth start small businesses in manufacturing, services or trading.
The scheme was run by the Department of Micro, Small and Medium Enterprises (MSME) and Textiles. At the state level, the Director of MSME acted as the nodal officer, while district officials handled local work. Loans were given through state-owned cooperative banks.
Karma Sathi Prakalpa at a glance
| Point | Details |
|---|---|
| Launched | September 2020 |
| Department | MSME and Textiles, Government of West Bengal |
| Loan | Soft loan of up to ₹2 lakh |
| Project subsidy | 15 percent, up to ₹25,000 |
| Interest subsidy | 50 percent of interest for up to 3 years for timely repayment (40 percent in other eligible cases) |
| Who could apply | Unemployed youth registered with the Employment Bank |
| Target | 1 lakh unemployed youth |
| Replaced by | Bhabishyat Credit Card scheme, from 1 April 2023 |
How Karma Sathi Prakalpa worked
- Application: Young people applied online on the Karma Sathi portal or submitted forms at the Block Development Office (rural areas) or the Sub-Divisional Office or Kolkata Municipal Corporation (urban areas).
- Project idea: Applicants proposed a small business in manufacturing, services or trading.
- Checking: District officials, with the Additional District Magistrate looking after MSME matters, checked the proposals.
- Loan: Selected applicants got a soft loan of up to ₹2 lakh from a state cooperative bank.
- Subsidy: A project subsidy of 15 percent, capped at ₹25,000, reduced the amount to be repaid.
- Interest help: Borrowers who repaid on time could get 50 percent of their interest back for up to three years.
Who could apply
- Unemployed young people from West Bengal.
- Registered with the state’s Employment Bank.
- With a viable business idea.
Because Employment Bank registration was a condition, many applicants first had to register there. Our Employment Bank registration guide explains how that works.
Business ideas that fitted the scheme
Karma Sathi Prakalpa was meant for small, practical businesses that a young person could run with a modest loan, such as:
- A grocery or stationery shop.
- Tailoring or garment work.
- A mobile repair or computer service centre.
- A small food stall or catering service.
- Poultry, dairy-linked or other agro-based units.
- Beauty parlour or salon services.
The idea was that a loan of up to ₹2 lakh, with a subsidy, could help such a unit start and earn enough to repay.
How many people benefited?
The scheme aimed to reach 1 lakh young people, but the actual numbers were much lower. An analysis by the IMPRI policy institute noted that about 656 people had benefited by November 2020, with about ₹9.82 crore disbursed, and the 2022 state budget speech mentioned 458 beneficiaries and ₹7.95 crore by December 2021. These were separate snapshots, but both show that reach was far below the target.
Why was Karma Sathi Prakalpa replaced?
The state replaced Karma Sathi Prakalpa with a bigger scheme, the West Bengal Bhabishyat Credit Card scheme, from 1 April 2023. The new scheme:
- Raised the maximum loan from ₹2 lakh to ₹5 lakh.
- Offered collateral-free loans with government support.
- Gave seed money of up to ₹25,000 to approved applicants.
- Covered more types of small business.
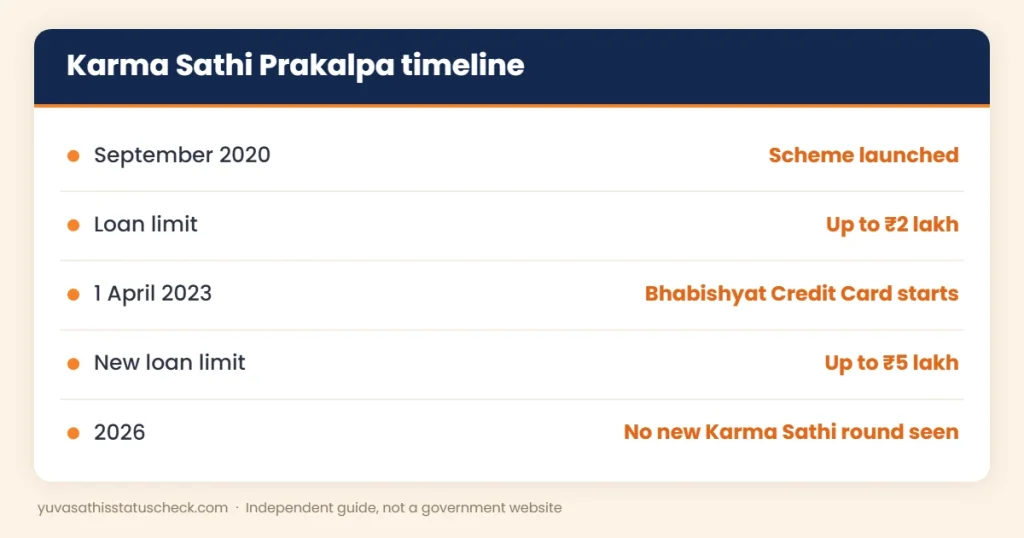
In simple words, Karma Sathi Prakalpa was the first version, and Bhabishyat Credit Card was the upgraded version, with a bigger loan and wider reach. For full details of the newer scheme, read our Bhabishyat Credit Card guide.
Common questions people still ask
Even years after the change, people keep asking similar questions about Karma Sathi Prakalpa. The most common are whether a fresh form has come out, whether the ₹2 lakh limit still applies and whether Employment Bank registration is still required. The short answers are: no new round has been seen, the newer state scheme had a higher limit, and each current scheme has its own rules. The comparison below shows how the two state schemes differ.
Karma Sathi Prakalpa vs Bhabishyat Credit Card
| Point | Karma Sathi Prakalpa | Bhabishyat Credit Card |
|---|---|---|
| Started | September 2020 | 1 April 2023 |
| Maximum loan | ₹2 lakh | ₹5 lakh |
| Subsidy / seed money | 15% subsidy, up to ₹25,000 | Up to ₹25,000 seed money |
| Collateral | Soft loan via cooperative bank | Collateral-free |
| Main condition | Employment Bank registration | Age and residence rules |
| Status in 2026 | Superseded; no new round seen | Status under the new government not clearly announced |
Is Karma Sathi Prakalpa open in 2026?
We have not seen any official notice of a new Karma Sathi Prakalpa application round in 2026. The scheme was superseded in 2023, and the new state government, which took office in May 2026, has not announced a revival.
Some websites still show “Karma Sathi Prakalpa online apply 2026” with forms and links. Be careful:
- Check that any link ends in .wb.gov.in.
- Do not pay any agent to “approve” a Karma Sathi loan.
- Do not share your bank PIN or OTP with anyone.
I had a Karma Sathi loan. What now?
If you took a loan under Karma Sathi Prakalpa:
- Keep repaying on time. A loan does not end because a scheme is replaced. Timely repayment also protects your credit record.
- Ask about interest subsidy. If you repaid on time, ask your bank whether any interest subsidy is due.
- Keep all papers. Save the sanction letter, repayment receipts and subsidy letters.
- Talk to your bank if you face trouble. Banks can sometimes reschedule repayments for genuine cases.
- Contact the district MSME office if you have a subsidy or record problem.
How to check an old Karma Sathi Prakalpa application
If you applied but never got a reply:
- Check the SMS and email you used when applying.
- Ask at the BDO office or SDO office where you submitted the form.
- Visit the cooperative bank branch named in any letter.
- Keep your application number ready.
Since the scheme was replaced, pending applications may not be processed under the old rules. In many cases, officials ask old applicants to apply afresh under the current scheme with updated documents. Ask the office whether you should apply under a newer scheme instead.
What the new government has announced for youth
The new government has focused more on jobs and allowances than on reviving the old loan scheme so far. The 2026-27 budget announced 1 lakh government vacancies, free coaching centres for competitive exams, startup funds and a monthly allowance for unemployed youth. In October 2026, reports said the state approved 14,454 posts across departments. If a new self-employment scheme is announced, it will most likely come through the MSME department.
Loan options for young people in 2026
If you want to start a business today, look at these options. Rules change, so always check the official website before applying.
| Option | What it offers (in general) | Where to check |
|---|---|---|
| Bhabishyat Credit Card (state) | Collateral-free loans up to ₹5 lakh, with seed money | Official state portal |
| PMEGP (central) | Subsidy-linked loans for new micro enterprises | PMEGP portal |
| PM Mudra Yojana (central) | Small business loans through banks in different categories | Mudra website |
| Startup support (state) | ₹40 crore incubation and ₹60 crore venture funds announced in Budget 2026-27 | State startup notices |
The 2026-27 state budget also announced startup funds. See our West Bengal budget 2026 summary for details.
Lessons from Karma Sathi Prakalpa
The low reach of Karma Sathi Prakalpa holds useful lessons for anyone applying for a youth loan today:
- Paperwork matters. Many applications stalled because documents were incomplete.
- Banks look for viability. A clear plan with real costs and income gets more attention.
- Follow-up helps. Applicants who stayed in touch with the office and bank moved faster.
- Training helps. Young people with some skill training found it easier to convince banks.
Use these lessons whatever scheme you apply for next.
Before you borrow: a quick self-check
- Do you know exactly what you will sell or make?
- Have you spoken to a few possible customers?
- Do you know your monthly costs, including rent and transport?
- Can you repay the monthly instalment even in a slow month?
- Do you have a family member or mentor who can advise you?
If you answer “no” to most of these, take a little more time to plan before applying.
Documents usually needed for a youth business loan
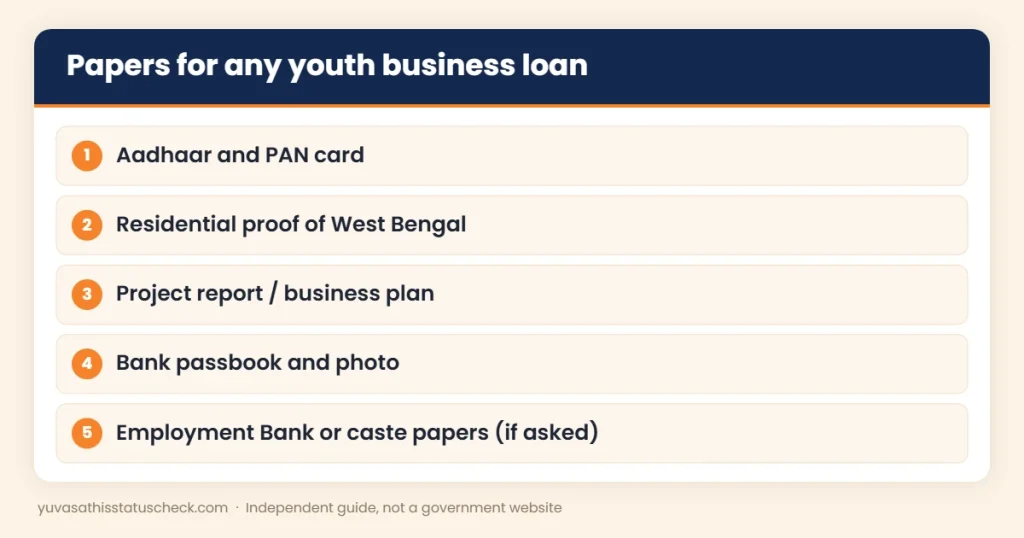
- Aadhaar card and PAN card.
- Residential proof; see our residential certificate West Bengal guide.
- Caste certificate, if you want category benefits; see our caste certificate West Bengal guide.
- A simple project report or business plan.
- Bank account details and passport-size photos.
- Employment Bank registration or proof of unemployment, if asked; see our unemployment certificate West Bengal guide.
Skill training before you start
A loan alone rarely makes a business succeed. Skills matter just as much. Before applying, consider:
- Short courses at government ITIs or polytechnics in your district.
- Skill development programmes run by the state or central government.
- Learning from a family member or local business owner who already runs a similar unit.
- Basic training in accounts, digital payments and marketing on social media.
Banks and departments often look more favourably on applicants who can show training certificates or work experience in the same field. Even a few weeks of training can make your project report more believable and your business more likely to survive the first year.
How to write a simple project report
Banks and departments want to see that your business can work. A short project report should cover:
- Business idea: what you will make or sell, or what service you will give.
- Location: where the business will run.
- Cost: machines, stock, rent and other start-up costs.
- Money plan: how much loan you need and how much you will put in yourself.
- Income: expected monthly sales and profit.
- Repayment: how you will repay the loan each month.
Keep it simple and honest. Ask the district MSME office or a bank officer for a sample format. A one or two page report with clear numbers is often better than a long document full of guesses.
Tips to get a youth business loan approved
- Start small. Ask for an amount you can repay from realistic earnings.
- Show your own share. Banks like to see that you are putting in some money yourself.
- Keep papers in order. Matching names and addresses on Aadhaar, PAN and bank records speed things up.
- Learn the basics. A short skill or business training course makes your application stronger.
- Keep your credit record clean. Repay any older loans on time.
- Follow up politely. Visit the bank and the office with your application number.
Mistakes to avoid
- Applying through unofficial websites that still use the old scheme name.
- Paying agents to get a loan sanctioned.
- Taking a bigger loan than your business can repay.
- Using the loan for personal spending instead of the business.
- Ignoring repayment reminders from the bank.
3 real-life examples
Sujit, 27, Hooghly: He took a loan under Karma Sathi Prakalpa in 2021 to open a mobile repair shop. He repaid on time and later asked his bank about the interest subsidy he was due.
Mitali, 30, Nadia: She applied for the scheme but got no reply. When she asked at her block office in 2026, she learned the scheme had been replaced, and she started preparing an application under a current loan scheme instead.
Anirban, 24, Kolkata: He had no business plan yet. He decided to register on the Employment Bank, look for a job and wait for the youth allowance, while learning skills for a future business.
Offices that can help
If you have questions about an old Karma Sathi Prakalpa loan or application, these offices can help:
- The bank branch that gave the loan or received your application.
- The Block Development Office (rural areas) or Sub-Divisional Office (urban areas).
- The district MSME office, which handles self-employment schemes at district level.
Take your application number, ID proof and any letters you received.
Business or allowance: which is right for you?
Not everyone wants to start a business. If you are still looking for a job, the state’s new monthly allowance for unemployed youth may help while you search: ₹3,000 for graduates and ₹2,000 for others, once the form opens. Read our Yuva Shakti scheme guide. If you have a clear business idea and can manage repayments, a loan scheme may suit you better.
Frequently asked questions
What was Karma Sathi Prakalpa?
A West Bengal self-employment scheme launched in September 2020 that gave soft loans of up to ₹2 lakh with a 15 percent subsidy (up to ₹25,000) to unemployed youth registered with the Employment Bank.
Is Karma Sathi Prakalpa still open in 2026?
We have not seen any new application round. It was superseded by the Bhabishyat Credit Card scheme from 1 April 2023.
What replaced Karma Sathi Prakalpa?
The West Bengal Bhabishyat Credit Card scheme, which raised the loan limit to ₹5 lakh.
Do I still have to repay my Karma Sathi loan?
Yes. A loan must be repaid as agreed even if the scheme has been replaced.
Who ran Karma Sathi Prakalpa?
The Department of MSME and Textiles, with loans given through state cooperative banks.
Was Employment Bank registration needed?
Yes. Applicants had to be unemployed youth registered with the Employment Bank.
What other loans can young people get?
Options include the state’s Bhabishyat Credit Card scheme and central schemes such as PMEGP and PM Mudra, subject to their current rules.
Should I pay an agent to get a Karma Sathi loan?
No. Never pay agents, and apply only through official channels.
Sources we checked
- IMPRI: Karma Sathi Prakalpa (2020): launch, department, loan, subsidy, eligibility, beneficiaries and replacement by Bhabishyat Credit Card.
- Millennium Post, 28 April 2025: Bhabishyat Credit Card loans up to ₹5 lakh from 1 April 2023.
- Karma Sathi Prakalpa portal: official scheme portal.
- PRS Legislative Research: West Bengal Budget 2026-27: startup funds.
Disclaimer: yuvasathisstatuscheck.com is an independent information website. It is not connected with the Government of West Bengal or any bank. This is general information, not financial advice; check official sources before applying for a loan.